FINWIRES · TerminalLIVE
FINWIRES

$TAP

11 stories mentioning TAPUpdated 19d ago

Every FINWIRES story that references TAP, newest first.

What are analysts saying about TAP?

Recent broker actions mentioned in FINWIRES coverage. Compiled from wire headlines; not investment advice.

What's the latest news on TAP?

Brown-Forman Maintains Full-Year Guidance as First-Quarter Sales Miss Views
US Markets

Brown-Forman Maintains Full-Year Guidance as First-Quarter Sales Miss Views

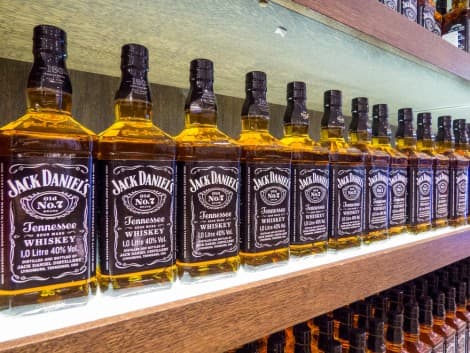
Brown-Forman (BF.A, BF.B) reiterated its guidance for fiscal 2027 organic sales on Wednesday as it flagged continuing consumer headwinds that drove weaker-than-expected first-quarter top-line.For the ongoing fiscal year, the parent of Jack Daniel's whiskey continues to expect roughly flat organic sales. Analysts in a FactSet poll are looking for full-year reported sales of $3.95 billion, compared with $3.93 billion in fiscal 2026.Brown-Forman continues to project a 3% to 5% decline in organic operating income for the current fiscal year.For the quarter ended July 31, revenue slipped 1% to $911 million, below Wall Street's $914.8 million view for the class B listing. Earnings per share rose to $0.38 from $0.36."We anticipate the operating environment for fiscal 2027 to remain challenging, as macroeconomic pressures and geopolitical instability continue to negatively impact consumer behavior and beverage alcohol consumption, particularly within developed markets," the company said in its earnings release.Analysts at RBC Capital Markets had seen a challenging first-quarter setup for the wine and spirits maker given a tough comparison and cautious consumer sentiment. In a note e-mailed Tuesday, RBC analysts pointed to severe US spirits headwinds reported by Brown-Forman's competitors, Diageo (DEO) and Pernod Ricard.Beer maker Molson Coors Beverage (TAP) last month reported a 3.3% annual drop in second-quarter net sales as heightened global macroeconomic headwinds weighed on consumer behavior. Earlier this year, Constellation Brands, the maker of Modelo and Corona, posted stronger-than-expected fiscal first-quarter results despite what its chief executive described as "a discerning and value-conscious consumer environment."In the US, consumer sentiment dropped in August amid concerns that inflation will continue to be high for the "foreseeable future," University of Michigan said Friday. Inflation concerns appear to be intensifying as renewed US-Iran hostilities have driven oil prices higher.Brown-Forman said its first-quarter net sales in the US dropped 3% year on year, driven by the end of the Korbel relationship, lower distributor inventories and volume declines for Jack Daniel's Tennessee Blackberry. Sales fell 6% in developed international markets and grew 11% in emerging markets.Sales of whiskey products were flat and tequila revenue plunged 12%, countering 20% sales growth in the ready-to-drink segment.Brown-Forman's class A and B shares rose 2.7% and 3.2%, respectively, in Wednesday trade. They are up 5.4% and 4.3% so far this year.

$BF.A$BF.B$DEO$STZ$TAP$TAP.A
Brown-Forman's Challenging First-Quarter Setup Likely Pressured Revenue, RBC Says
US Markets

Brown-Forman's Challenging First-Quarter Setup Likely Pressured Revenue, RBC Says

Brown-Forman's (BF.A, BF.B) challenging fiscal first-quarter setup likely pressured its top-line amid a tough comparison and cautious consumer sentiment, RBC Capital Markets said in a note e-mailed Tuesday.The wine and spirits maker is scheduled to release its quarterly results on Wednesday.RBC is projecting revenue of $919.4 million, down from $924 million a year earlier, while analysts in the FactSet survey are looking for about $915 million. The brokerage expects adjusted earnings per share of $0.37, matching the FactSet-polled consensus, compared with $0.36 a year ago.The first-quarter setup for the parent of Jack Daniel's whiskey includes the "toughest revenue comparison of the year" as Brown-Forman laps the initial US launch of JD Tennessee Blackberry and a major US distributor transition, RBC co-head of global consumer and retail research Nik Modi said."Overall, we remain cautious on (Brown-Forman) as the company works through the burden of lapping Blackberry load-in and distributor transitions, with still muted category dynamics, and mounting consumer pressures," Modi wrote.Distributors are concerned about Brown-Forman's "ability to lap the strong launch of Jack Daniels Blackberry" and expect increased promotional activity in the spirits market over the coming months."Peer reads and our distributor checks confirm a challenged US spirits backdrop with subdued consumer confidence and affordability pressures," Modi said.Brown-Forman's competitors Diageo and Pernod Ricard have reported "severe US spirits headwinds," according to RBC.Last week, a survey by the University of Michigan showed that US consumer sentiment dropped in August amid concerns that inflation will continue to be high for the "foreseeable future." The Conference Board separately said that consumer confidence fell in August with a "more pessimistic" outlook for business conditions and the labor market ahead.In June, Brown-Forman said it anticipated fiscal 2027 organic sales to be roughly flat after the metric was unchanged for the year ended April 30. The Street is looking for reported sales of $3.95 billion for the ongoing fiscal year.Molson Coors Beverage (TAP) last month reported a 3.3% annual drop in second-quarter net sales as heightened global macroeconomic headwinds weighed on consumer behavior.

$BF.A$BF.B$TAP
Wire

UBS Adjusts Molson Coors Beverage PT to $45 From $40, Maintains Neutral Rating

Molson Coors Beverage (TAP) has an average rating of hold and mean price target of $45.40, according to analysts polled by FactSet.Price: $42.90, Change: $+0.49, Percent Change: +1.14%

$TAP
Consumer Staple Companies Likely Saw Another 'Tricky' Quarter, UBS Says
US Markets

Consumer Staple Companies Likely Saw Another 'Tricky' Quarter, UBS Says

US consumer staple companies likely faced another "tricky" quarter, with earnings growth seen impacted to a certain extent by inflation, UBS Securities said in a note e-mailed Thursday.The brokerage expects second-quarter results from most of the group it covers to be "okay," analysts Peter Grom and Sona Fernandes said in a note to clients. While inflation is expected to have limited bottom-line growth "to a degree," the situation is more than reflected in Wall Street's estimates, according to the note."While we continue to believe fundamental visibility remains key to any investment case in staples, this has become increasingly priced in across the group making risk/reward far more difficult to assess on the surface," the analysts said. "This makes the setup into (second-quarter) earnings season tricky once again, but in some ways we think the playbook remains unchanged with fundamental visibility continuing to trump valuation."Coca-Cola (KO), Keurig Dr Pepper (KDP), Monster Beverage (MNST), and Colgate-Palmolive (CL) are among the major names with favorable setups heading into the latest results, according to UBS.Coca-Cola offers the "highest degree of fundamental visibility" among the group, Grom and Fernandes said. The beverages giant is poised for a strong print amid continued momentum in its top-line, according to the note.For Keurig Dr Pepper, stronger growth from US refreshment beverages is likely to continue to drive upside despite "some concerns" around the company's coffee business, the analysts said. UBS expects solid revenue momentum for Colgate-Palmolive despite input cost uncertainty linked to the Middle East conflict.While most Monster Beverage investors expect another strong quarterly print, the company will have to offer proof that it is capable of sustaining sales momentum, especially as competitive pressures mount and comparisons get tougher, according to the note.Procter & Gamble (PG), Elf Beauty (ELF), and Celsius (CELH) are among the most debated stocks, according to UBS.The brokerage sees Procter & Gamble's risk-reward profile as skewed to the upside despite an anticipated conservative fiscal 2027 outlook. Elf Beauty's core business volatility persists and "sentiment/stock performance will continue to hinge on the base business," Grom and Fernandes said.For Celsius, the latest results itself are unlikely to "meaningfully alter the debate," which is expected to be focused on whether the company's core business can show signs of stabilization, the analysts wrote.Molson Coors Beverage (TAP), Energizer (ENR), and Boston Beer (SAM) likely faced unfavorable setups due largely to deteriorating category trends, according to the note."Given scarcity of growth and (long-term) algorithms increasingly in question looking ahead, we think relative valuation is far less critical at this juncture and think companies that can outline credible avenues to deliver top- and bottom-line growth will continue to outperform," Grom and Fernandes said.Price: $84.76, Change: $+2.31, Percent Change: +2.80%

$CELH$CL$ELF$ENR$KDP$KO$MNST$PG$SAM$TAP
Wire

BofA Adjusts Price Target on Molson Coors Beverage to $40 From $42

Molson Coors Beverage (TAP) has an average rating of hold and mean price target of $45.45, according to analysts polled by FactSet.Price: $39.46, Change: $+0.72, Percent Change: +1.86%

$TAP
Wire

Molson Coors Unit Launches Private Offering of Canadian Dollar Notes

Molson Coors Beverage's (TAP) international unit launched a private offering of Canadian dollar-denominated senior notes to be sold only to Canadian investors.Net proceeds will be used for general corporate purposes, including repaying 500 million Canadian dollars ($363.6 million) of 3.44% senior notes due 2026, the company said Wednesday in a statement.The offering is expected to close around May 27.Price: $42.89, Change: $+0.94, Percent Change: +2.24%

$TAP
Wire

Morgan Stanley Adjusts Molson Coors Beverage Price Target to $46 From $52, Maintains Equal Weight Rating

Molson Coors Beverage (TAP) has an average rating of Hold and mean price target of $46.20, according to analysts polled by FactSet.Price: $41.31, Change: $-0.83, Percent Change: -1.97%

$TAP
Research

Research Alert: CFRA Maintains Sell Opinion On Shares Of Molson Coors Beverage Company

CFRA, an independent research provider, has providedwith the following research alert. Analysts at CFRA have summarized their opinion as follows:We lower our 12-month target by $5 to $35, based on a 2027 P/E of 7.0x, a justified discount to TAP's five-year average forward P/E of 11.4x. We raise our adjusted EPS estimates by $0.20 to $4.90 for '26 and by $0.10 to $5.10 for '27. Following TAP's Q1 earnings release, we are lowering our price target and maintaining a Sell opinion on the shares. TAP posted Q1 adjusted EPS of $0.62 vs. $0.50 (+24%), well ahead of the $0.36 consensus. The beat was due to stronger-than-expected sales and margins, as net sales rose 2.0% to $2.35B ($25 above consensus) on a 2.9% drop in financial volume and gross margin expanded 130 bps to 38.2% (350 bps ahead of consensus). While TAP's Q1 earnings were well ahead of expectations, the fact that it didn't increase full-year guidance raises concerns that the balance of the year will be weaker than previously anticipated, with positive foreign exchange impacts likely to be less favorable than in Q1. We struggle to identify a catalyst and see the demand environment remaining challenging.

$TAP
Wire

Goldman Sachs Adjusts Price Target on Molson Coors Beverage to $50 From $48

Molson Coors Beverage (TAP) has an average rating of hold and mean price target of $46.15, according to analysts polled by FactSet.Price: $42.37, Change: $-0.38, Percent Change: -0.88%

$TAP
Research

Research Alert: Tap: Q1 Earnings Well Ahead Of Expectations; 2026 Guidance Unchanged

CFRA, an independent research provider, has providedwith the following research alert. Analysts at CFRA have summarized their opinion as follows:Molson Coors (TAP) posted Q1 adjusted EPS of $0.62 vs. $0.50 (+24%), well ahead of the $0.36 consensus. The beat was due to stronger-than-expected sales and margins, as net sales rose 2.0% to $2.35B ($25M above consensus) on a 2.9% drop in financial volume, partially offset by positive impacts from price/sales mix (+3.0%) and currency (+1.9%). Gross margin expanded 130 bps to 38.2% (350 bps ahead of consensus). The decline in financial volume reflected ongoing industry challenges, with U.S. brand volumes falling 3.5% due to lower share performance in core and value segments, while Canada experienced a 4.0% decline led by broader industry weakness. TAP maintained guidance for a full-year underlying EPS decline of 11%-15%, implying EPS of approximately $4.61-$4.82, versus the current consensus of $4.71 and the $5.42 earned in 2025. TAP shares are currently trading 5% higher in pre-market trading following the release. TAP's margin performance was notably strong, with COGS remaining flat despite lower volumes.

$TAP
Wire

Evercore ISI Adjusts Molson Coors Beverage Price Target to $47 From $50, Maintains Outperform Rating

Molson Coors Beverage (TAP) has an average rating of Hold and mean price target of $46.55, according to analysts polled by FactSet.Price: $44.01, Change: $-0.28, Percent Change: -0.64%

$TAP

Track with the FINWIRES app suite

